Beta Free for 3 months · shipping September · company inquiry only
Accuracy live Loading live catalogue results… Full report →

Beta Treasury & FX

OrbaLM

Private desk runtime for treasury and FX — private chat and an Excel task pane, with governed calculation tools that own the numbers.

How it works — what OrbaLM is, what tools do, and what Beta includes.

Accuracy Governed calculators are verified daily against a public literature catalogue. See live pass rates
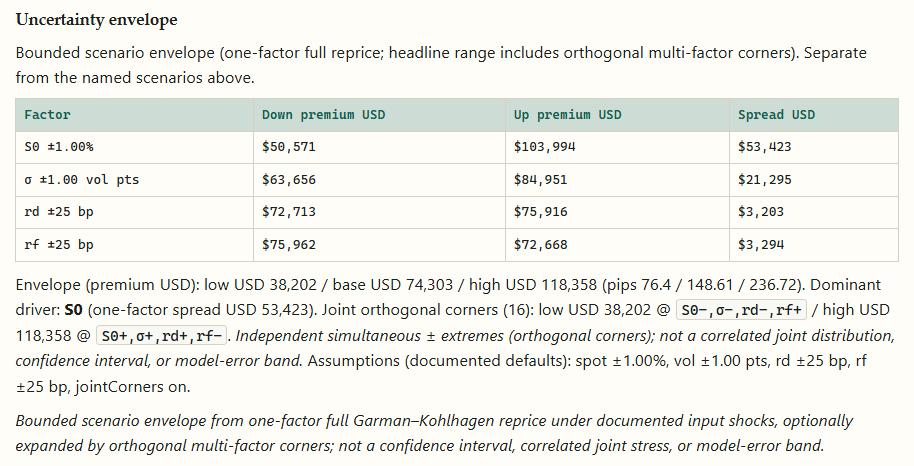
OrbaLM gk-math uncertainty envelope for a Sheet 1 EUR/USD Garman-Kohlhagen call: factor table, low/base/high premium, and dominant driver S0
Real tool output · FX options Bounded scenario envelope from the Sheet 1 EUR/USD call in the Treasury test workbook: one-factor Garman–Kohlhagen reprices plus joint orthogonal corners, with spot as the dominant driver — not a confidence interval.

Surfaces

Screenshots from real governed-tool reports — the same chat chrome and Excel task pane desks use, populated with Sheet 1–4 and JSON examples.
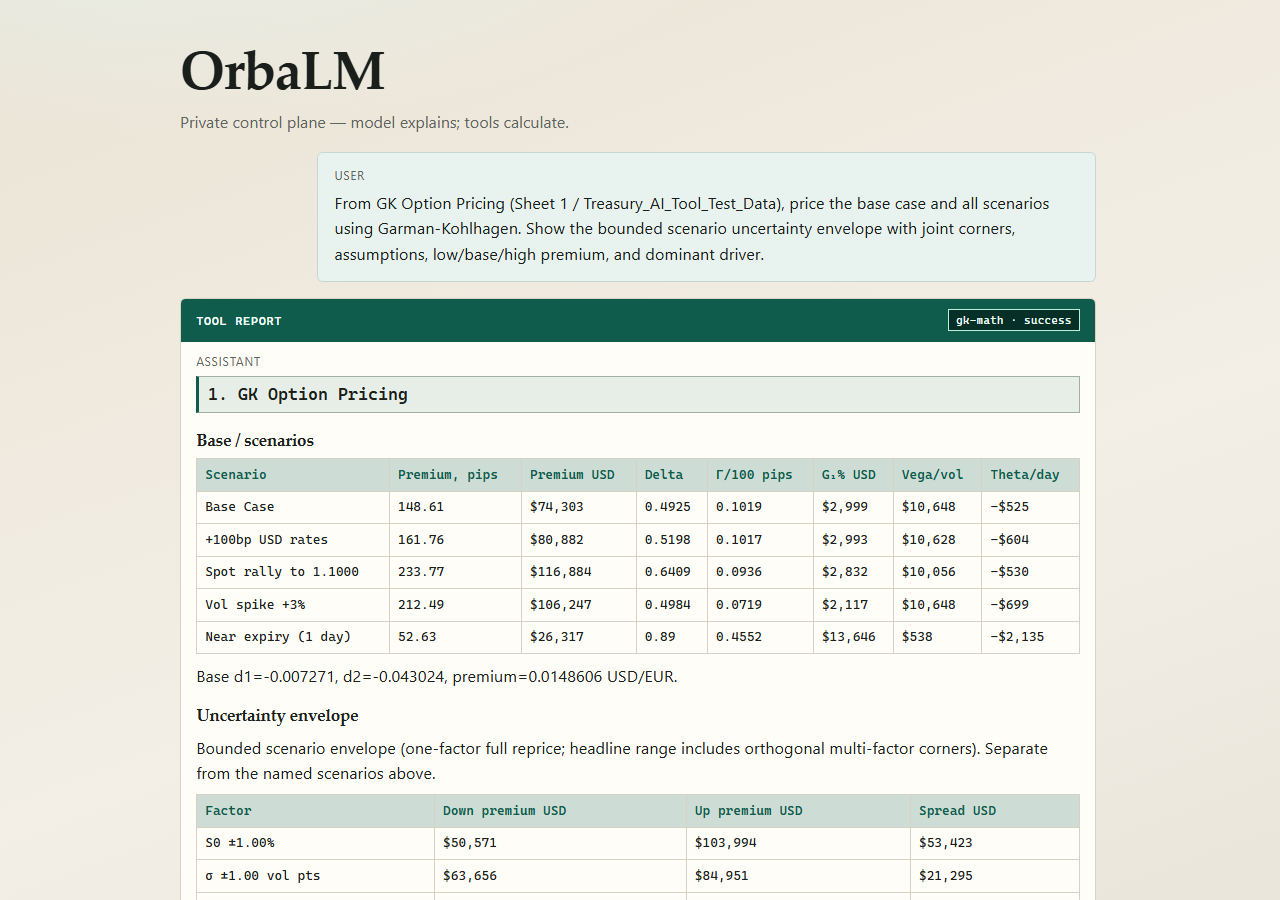
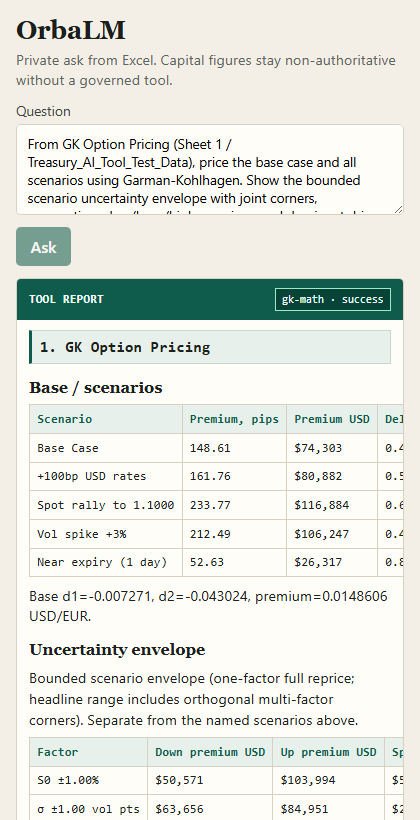
OrbaLM private chat showing a user ask and gk-math tool report for Sheet 1 FX options
Private chat · FX options Chat thread with a labelled tool report for Sheet 1 Garman–Kohlhagen: premiums, Greeks, and the uncertainty envelope assembled from the calc tool, not free-form model prose.
OrbaLM Excel task pane showing the same gk-math tool report and uncertainty envelope
Excel task pane · FX options The same Sheet 1 tool report in the Excel add-in: ask from the workbook, get a practitioner report with pack and tool provenance in the pane footer.
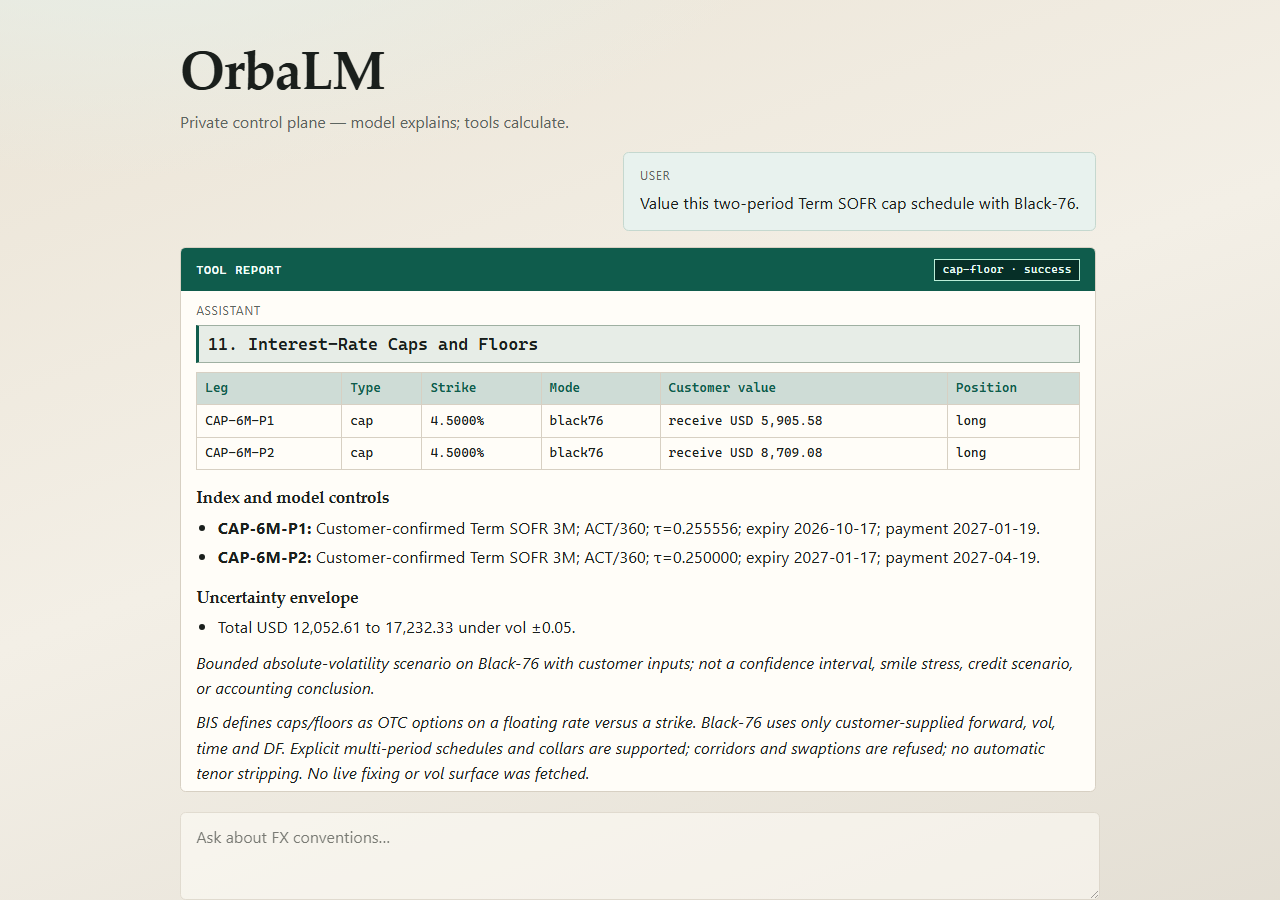
OrbaLM private chat showing a multi-period Term SOFR cap valued with Black-76
Private chat · Caps / floors Two-period Term SOFR cap schedule priced leg-by-leg with Black-76 from customer forwards and vols — explicit periods only, no automatic tenor stripping.
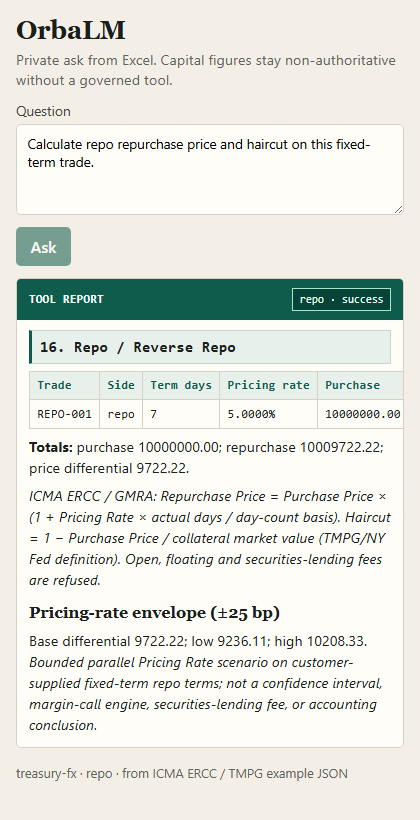
OrbaLM Excel task pane showing ICMA ERCC repo repurchase price and haircut report
Excel task pane · Repo Fixed-term EUR repo: ICMA ERCC repurchase price, price differential, and TMPG-style haircut from purchase vs collateral value, with a ±25 bp pricing-rate envelope.

Governed calc tools

Real captures from each shipped calc tool. Every image is a tool report (Sheet 1–4 fixtures or documented JSON examples) — see Coverage for the full matrix.
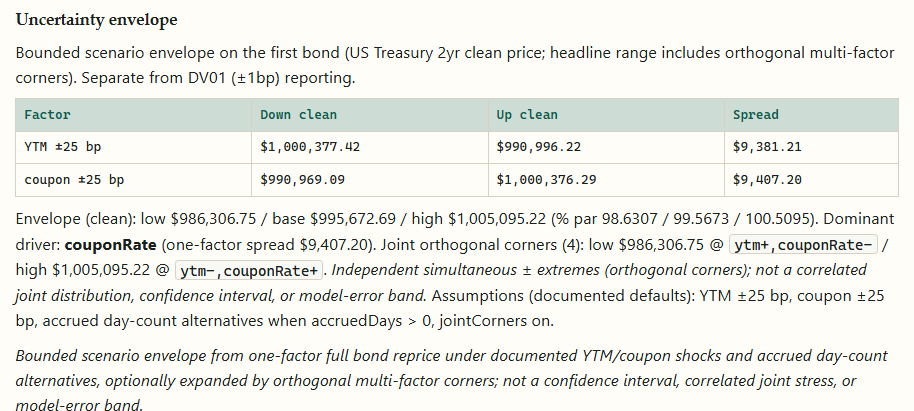
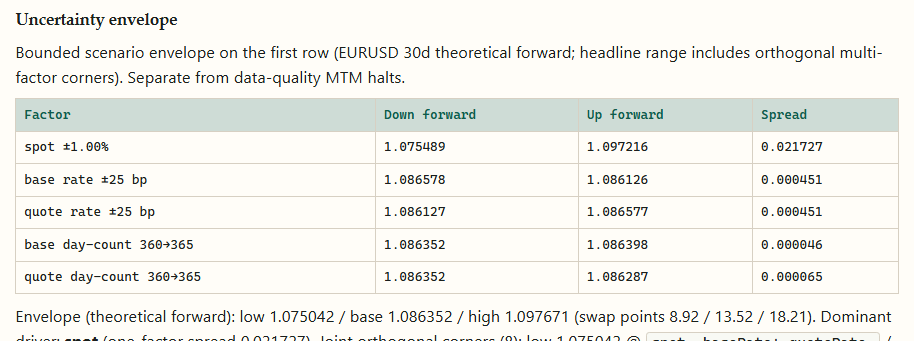
gk-math bounded scenario envelope with joint orthogonal corners for EUR/USD call
FX options Sheet 1 EUR/USD call: Garman–Kohlhagen premium and Greeks, with spot/vol/rate shocks and 16 joint orthogonal corners.
bond-math bounded scenario envelope for Sheet 2 bond book
Bonds Sheet 2 book: dirty/clean price, duration, convexity, and DV01, plus a yield-shock envelope on the first bond.
fx-forward bounded scenario envelope for Sheet 3 CIP forwards
FX forwards Sheet 3 CIP forwards: theoretical forward, swap points, MTM, and triangular-arb checks with a spot/rate envelope.
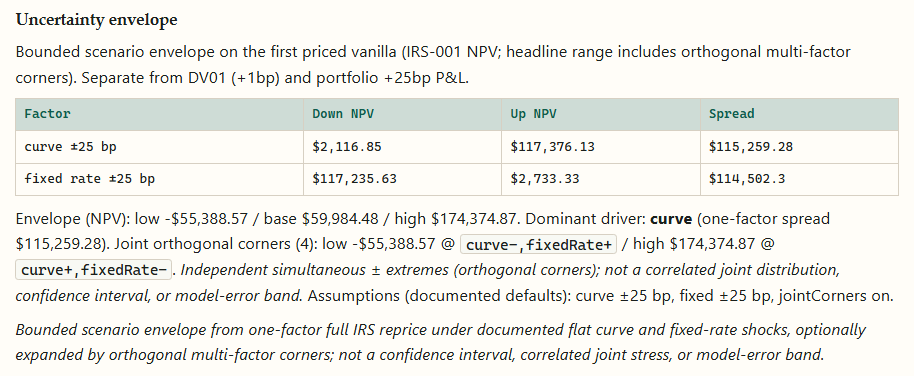
irs-math bounded scenario envelope for Sheet 4 SOFR swaps
Interest-rate swaps Sheet 4 SOFR IRS: curve bootstrap, NPV and DV01, with a parallel curve-shock envelope on the first vanilla.
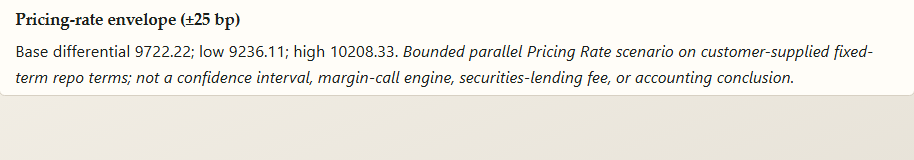
repo pricing-rate envelope for fixed-term EUR repurchase
Repo ICMA ERCC repurchase price and TMPG haircut on a 7-day EUR repo, with a ±25 bp pricing-rate differential envelope.
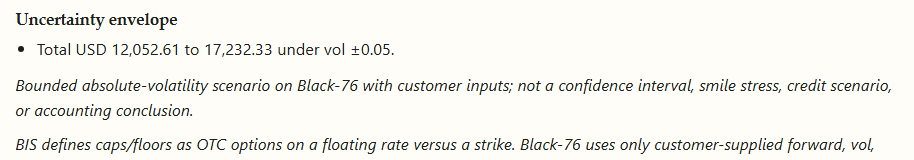
cap-floor volatility envelope for a two-period Term SOFR cap
Caps / floors Multi-period Term SOFR cap: Black-76 on explicit periods, with a ±0.05 absolute volatility envelope on the book total.
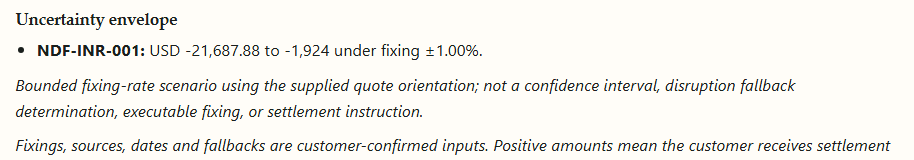
ndf fixing-rate envelope for INR cash settlement
NDFs INR non-deliverable forward: USD cash settlement from contract vs fixing, with quote orientation and a fixing-rate envelope.
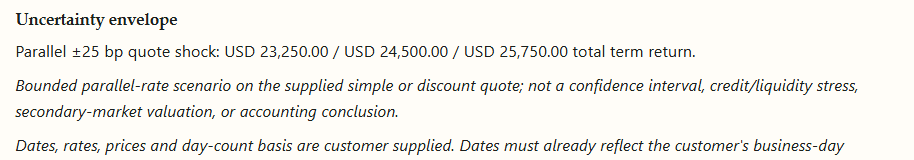
money-market rate envelope for deposit and commercial paper
Money markets USD deposit and commercial-paper yields under simple add-on and bank-discount conventions, with a ±25 bp rate envelope.
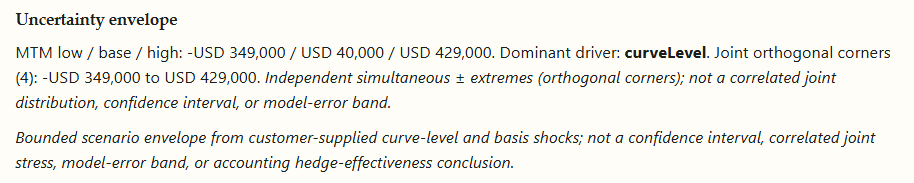
commodity-hedge spot and basis envelope for LME Copper forward
Commodity hedge LME Copper physical buy hedged with a forward: curve MTM, location basis, and joint spot/basis scenario corners.
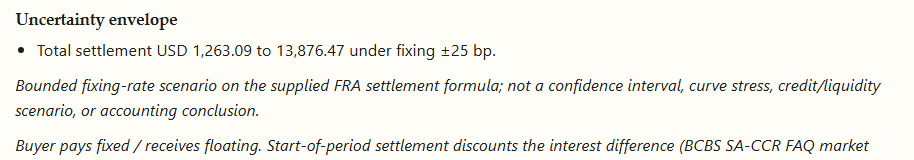
fra fixing envelope for a 3x6 Term SOFR forward-rate agreement
FRAs USD 3×6 FRA: discounted start-of-period settlement from contract vs fixing on ACT/360, with a ±25 bp fixing envelope.
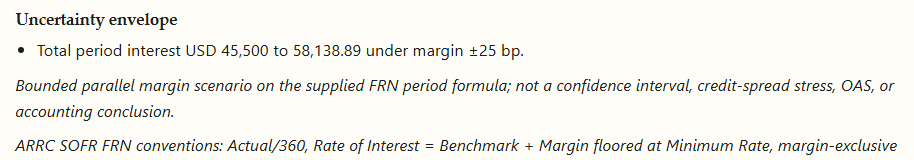
frn margin envelope for SOFR Index floating-rate note interest
FRNs SOFR Index FRN period interest via the ARRC compounded-index formula plus margin, with a margin-shock envelope.
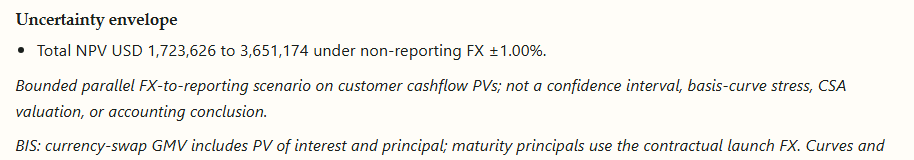
ccs FX envelope for AUD/USD cross-currency swap MTM
Cross-currency swaps AUD/USD CCS with interest and principal legs discounted and converted at customer FX, plus an FX-shock envelope.
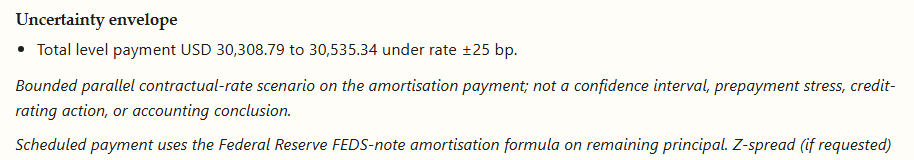
amortising-debt rate envelope for level-payment loan present value
Amortising debt Level-payment schedule and flat-discount present value on a USD facility, with a ±25 bp discount-rate envelope.
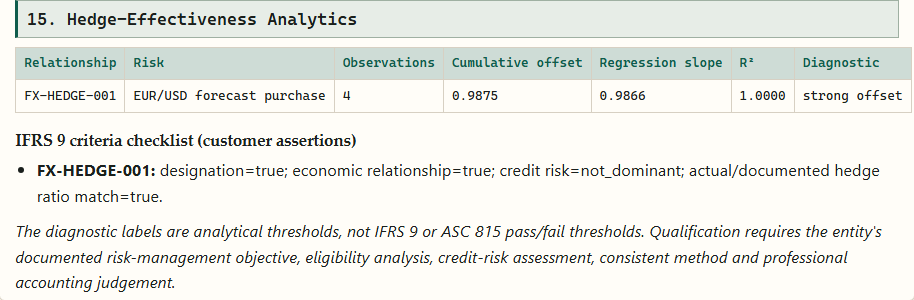
hedge-effectiveness regression and IFRS 9 checklist for EUR/USD forecast hedge
Hedge effectiveness EUR/USD forecast hedge: offset regression (slope, R²) plus an IFRS 9 qualitative checklist — diagnostic only, not an accounting qualification.

Evidence that stays current

OrbaLM pairs first-party desk literature with an allowlist of official financial and regulatory sources across treasury, markets, risk, and financial technology.

Beta offer

Eligibility

Request Beta access

Company domain required.

Berta is Rondanini Publishing's AI assistant. Conversations may be recorded to improve the service. Privacy